
Financing for Franchised Hotels, from Construction to Refinance
Building a new flag, buying a hotel to reposition or refinancing one that’s stabilized? AVANA’s franchise hotel financing runs from $1MM to $30MM through four programs. Apply once, and we match your hotel to the one that fits.
Soft quote in 1–2 business days. One application covers every AVANA program.
Which Hotel Loan Fits Your Project?
SBA 504 finances projects up to $20MM total, conventional loans run from $1MM to $15MM, and bridge and construction loans go up to $30MM.
You're Building, Expanding or Converting a Hotel
Ground-up builds, expansions, brand conversions and major renovations or PIPs ahead of stabilization go to hotel construction loans. Funds are drawn as work is completed.
You're Buying or Repositioning a Hotel in Transition
A bridge loan funds a hotel acquisition, PIP completion or a refinance before stabilization. It’s interest-only for up to 3 years.
Your Hotel Is Stabilized and Earning
A conventional term loan refinances maturing debt or buys a hotel with proven cash flow. It’s fixed for five years, with no prepayment penalty.
You'll Run the Hotel Yourself
If you’ll operate the hotel, SBA 504 can finance up to 90% of the project. It needs majority owner occupancy and brand or franchise approval.
Hotel Loan Eligibility
- The hotel is franchised under a major brand
- You have 5+ years in hospitality or commercial real estate for Bridge and Construction, or 3+ years of operating history for Conventional
- Guarantors have a FICO score of 680 or higher
- For an operating hotel, you can provide STR reports
- Principals can provide a full-recourse guaranty
What We Don't Finance for Hotels
Ground-up construction of independent hotels, first-time sponsors on bridge loans and projects without a credible exit plan. SBA 504 doesn’t fund working capital or inventory.
What You Can Finance
- Acquisition of existing hotels or portfolios
- Partner buyouts and recapitalizations
- Refinancing, including cash-out for qualified purposes
- Ground-up construction and brand-mandated PIPs
- Room, lobby, F&B and energy-efficiency upgrades
Franchise Hotel Financing Programs
Up to $20MM total project and up to 90% financing (85% special-use) for hotels you operate. The SBA debenture is fixed for up to 25 years.
$1MM–$15MM, up to 65% of value on hotels. Fixed for five years at the 5-Year CMT + 2.00%–3.00%, with no prepayment penalty.
$10MM–$30MM at 1-Month Term SOFR + 4.50%–7.00%. Interest-only for up to 3 years, with annual extension options.
$5MM–$30MM through the AVANA–Oaktree and AVANA–IHG programs. Interest-only on drawn funds, for up to 3 years.
What Lenders Look at on a Hotel Loan
Hotels are underwritten as operating businesses, not just real estate. Expect questions on these five points.
Brand and Franchise
Financing is for franchised hotels. Conventional loans cover Marriott, Hilton, IHG and Hyatt brands, and SBA 504 needs brand or franchise approval.
Occupancy and ADR
Lenders underwrite occupancy, ADR and brand standards. Send STR reports, plus an STR Trend Report for a brand conversion.
Debt Service Coverage
Conventional hotel loans need net operating income of at least 1.35x debt service, compared with 1.25x for most other property types.
PIP Scope and Budget
For a brand-mandated PIP or upgrade, send the scope of work and a budget with your application.
Sponsor Experience
Bridge and Construction loans need 5+ years in hospitality or commercial real estate. Conventional asks for 3+ years of operating history.
How Hotel Financing Works
Soft Quote
Send your application. You get a soft quote within 1–2 business days.
Letter of Intent
For Conventional, Bridge and Construction deals that fit, a Letter of Intent typically follows within 3–5 business days.
Underwriting
Third-party reports and final credit approval. The appraisal, environmental report and property condition report drive most of the timeline.
Closing
About 30–45 days from a signed LOI for Conventional, about 45 days for Bridge and Construction, and about 45–75 days for SBA 504.
Why Borrowers Work with AVANA
What You'll Need
At Application
Last year’s tax return or financial statement, plus a trailing 12-month P&L and balance sheet.
During Prescreen
An executive summary or offering memorandum, and an organizational chart, which is required before a Letter of Intent.
Financials
3 years of tax returns or historical financial statements, a T-12 dated within 90 days, a debt schedule and the current rent roll for leased assets.
Hotels
STR reports, plus an STR Trend Report covering as many years as you have for a brand conversion.
Each Guarantor
A personal financial statement with a schedule of real estate, a personal debt schedule, a resume and 3 years of personal tax returns.
Improvements and Refinances
Improvements: the scope of work and a budget.
Refinances: the current loan balance and status, prepayment penalty details and your cost basis.
Hotel Loans We've Helped Close
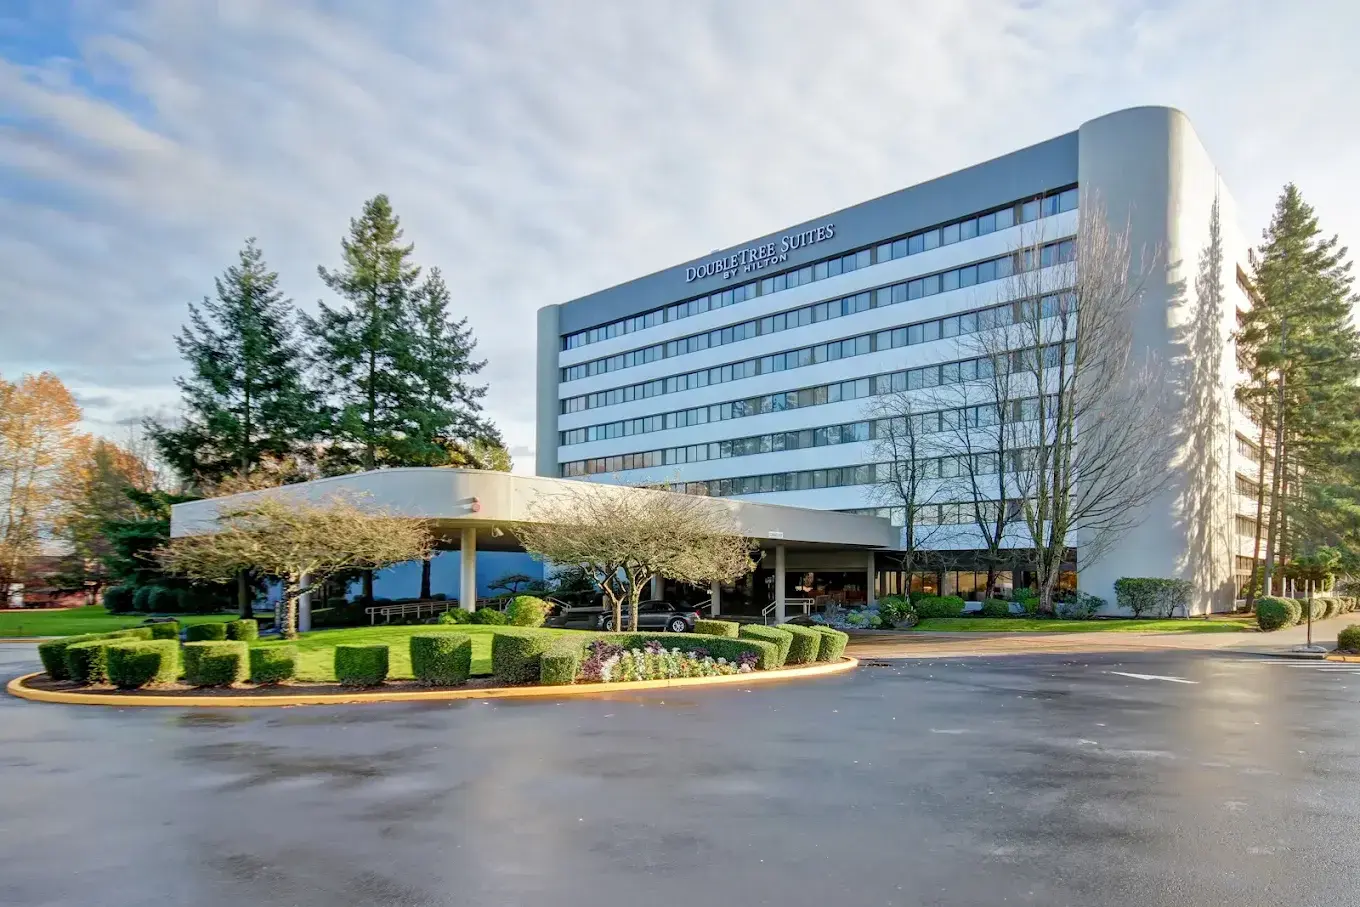


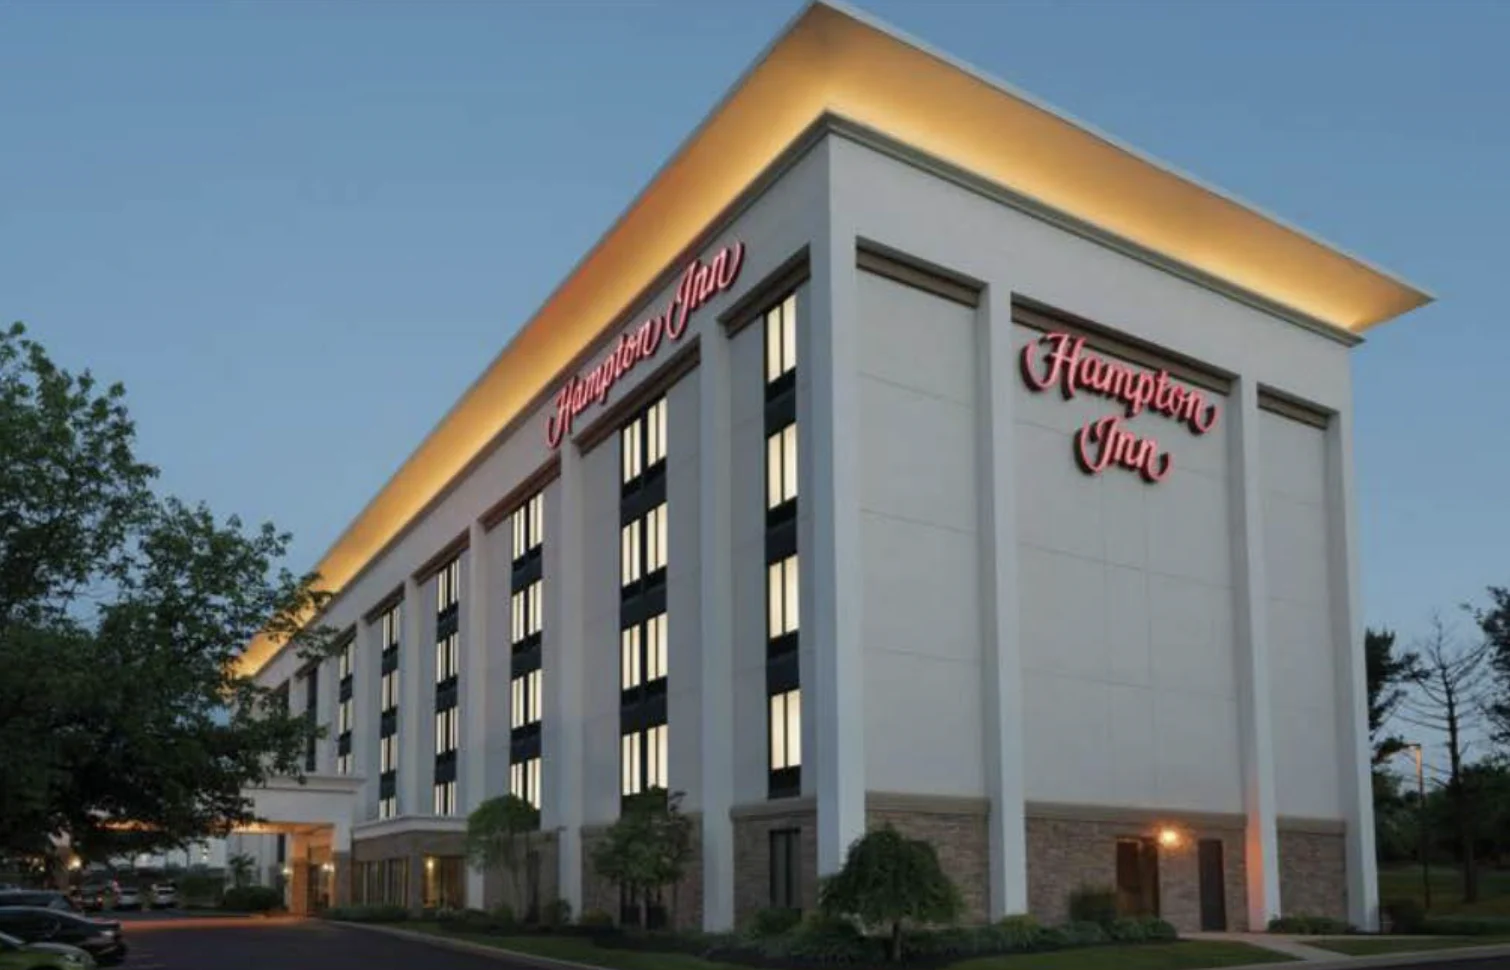
142-room Inn – Reading
Hotel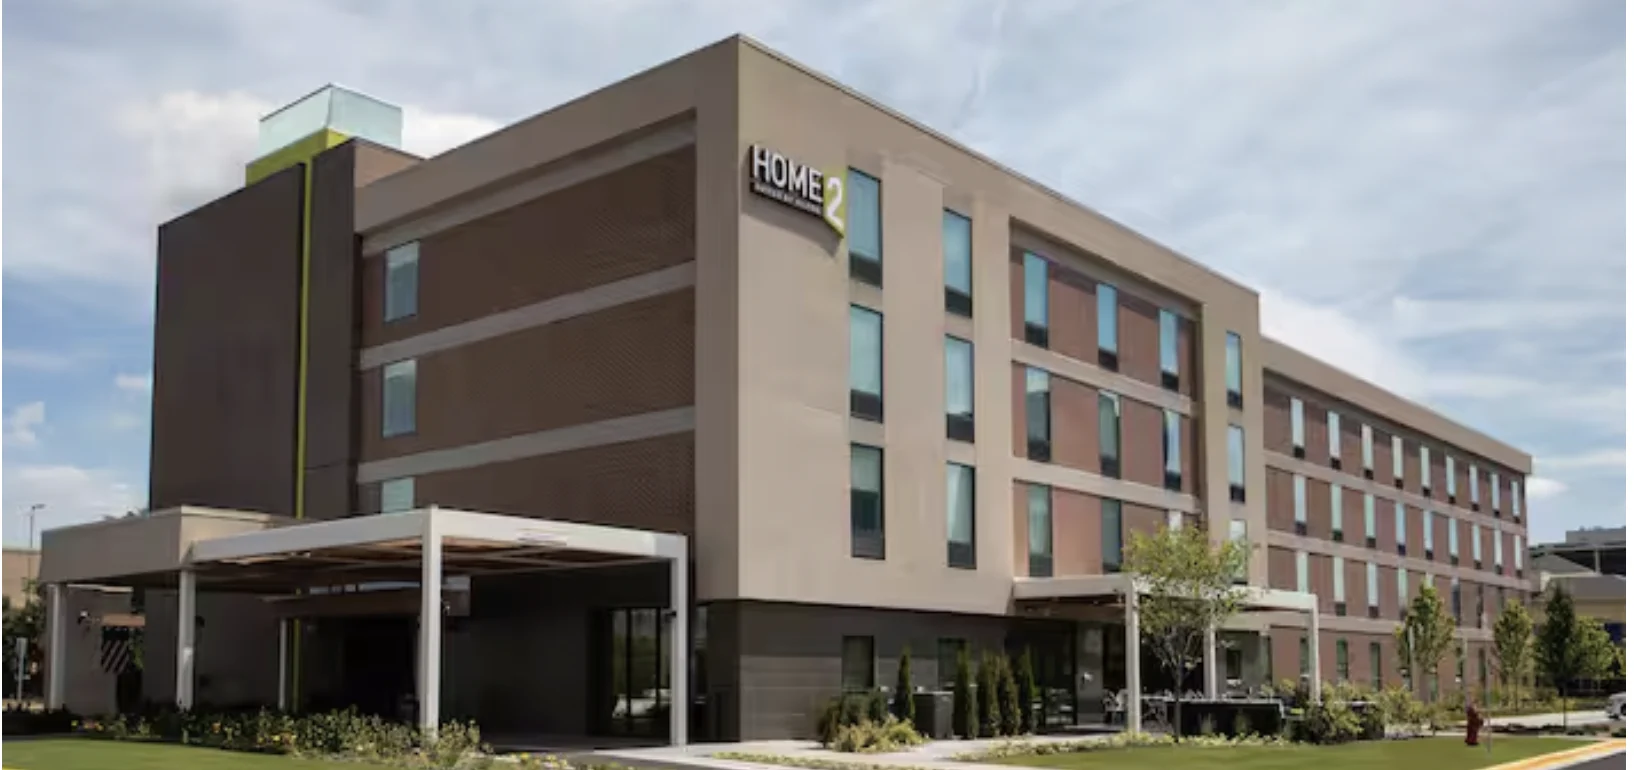
107-room Home2 Suites Deal
Acquisition
Nashville Hotel Deal
ConstructionHotel Loan FAQs
How much do I need to put down to buy a hotel?
As little as 10% with SBA 504 if you'll operate the hotel, or at least 35% with a conventional loan. SBA 504 rises to 15% for startups or special-purpose property, and to 20% if both apply.
Conventional hotel loans go up to 65% of value. Bridge loans cap at the lesser of 75% as-is or 70% as-stabilized value. See how SBA 504, Conventional and Bridge compare on our loan to buy commercial property page.
Do I need STR reports to get a hotel loan?
Yes, for an operating hotel. Lenders underwrite occupancy, ADR and brand standards, and STR reports are on the document checklist for hotel deals.
For a brand conversion, also send an STR Trend Report covering as many years as you have. A ground-up build has no history yet, so pre-qualification starts with the brand, location, project cost and exit plan.
Which hotel brands do you finance?
Franchised hotels under major brands. Conventional loans cover Marriott, Hilton, IHG and Hyatt brands, and construction covers select-service and limited-service hotels under major brands.
The AVANA–IHG construction program is built for Holiday Inn, Holiday Inn Express, EVEN Hotels, Avid Hotels and Atwell Suites. See hotel construction loans for details.
Can I finance a brand-mandated PIP?
Yes. Brand-mandated PIPs and room, lobby, F&B and energy-efficiency upgrades are eligible uses. A bridge loan can fund PIP completion before the hotel stabilizes.
Construction financing covers major renovations or PIPs ahead of stabilization, released in draws as the work is done. Send the scope of work and a budget with your application.
Can I refinance my hotel and take cash out?
Yes, for qualified purposes. Conventional loans refinance stabilized hotels up to 65% of value, with net operating income covering debt service at least 1.35x.
SBA 504 can refinance an owner-operated hotel that meets SBA use criteria and has operated for at least two years. A bridge loan can refinance a hotel before it stabilizes. See every option on our commercial mortgage refinancing page.
Can I buy out my partner in a hotel?
Yes. Partner buyouts and recapitalizations are an eligible use of hotel financing. A conventional term loan can refinance the hotel and fund the buyout, within the 65% limit.
The remaining owners typically provide the guaranty. List everyone with 20% or more ownership, plus the proposed guarantors, in your application.
Get a Soft Quote on Your Hotel Loan
Tell us the brand, the location, the amount you need and your plan for the hotel. We’ll come back with a soft quote within 1–2 business days.
Our Team
Chief Lending Officer