Commercial Real Estate Lending, Built for Credit Unions
AVANA CUSO helps credit unions strategically grow commercial real estate exposure through participation lending designed specifically for the credit union model.
One Platform Connecting CRE Borrowers With Credit Union Capital
We originate, underwrite and service commercial real estate loans, then offer them to partner credit unions as participations, so borrowers get financing and credit unions get well-documented CRE assets with ongoing oversight.
Bring a CRE Deal
SBA 504, conventional, bridge and construction loans for owner-occupied and investor-owned property, from $1MM to $30MM.
Underwrite, Close & Service
Disciplined credit review, documentation and servicing for the life of the loan.
Participate & Monitor
Review opportunities, keep approval authority and get post-close reporting through the Credit Union Portal.
Three Paths, One Connected Platform
For Credit Unions
Grow earning assets and diversify beyond your local footprint with CRE loan participations supported by documented workflows, servicing infrastructure, and reporting tools.
Explore Credit Union ServicesFor Borrowers
Finance owner-occupied or investor-owned commercial property from $1MM to $30MM through our credit union partnership network. We’ll guide you through prescreen requirements up front.
Explore Loan ProgramsFor Brokers
Submit deals through a defined prescreen process with clear requirements and consistent follow-up. If the opportunity fits, it moves through a structured workflow.
Explore Broker ProgramUse One Service or the Whole Platform
Loan Participation
Loan Origination
Credit Administration
Loan Servicing
Loan Programs We Support

For a building your business occupies (51% or more). Up to 90% of project cost (85% special-use) and up to $20MM total, with the SBA debenture fixed for up to 25 years.

For a stabilized, income-producing property. $1MM–$15MM, fixed for five years at the 5-Year CMT + 2.00%–3.00%, up to 75% of value, with no prepayment penalty.

For a property in transition or a deal that needs to close fast. $10MM–$30MM, interest-only for up to 3 years at 1-Month Term SOFR + 4.50%–7.00%.

For franchised hotels: ground-up builds, expansions, brand conversions and major renovations or PIPs. $5MM–$30MM, with interest only on drawn funds.
Financing by Property Type
Proven Success Stories
38-Unit Multifamily in Newark, NJ
Multifamily
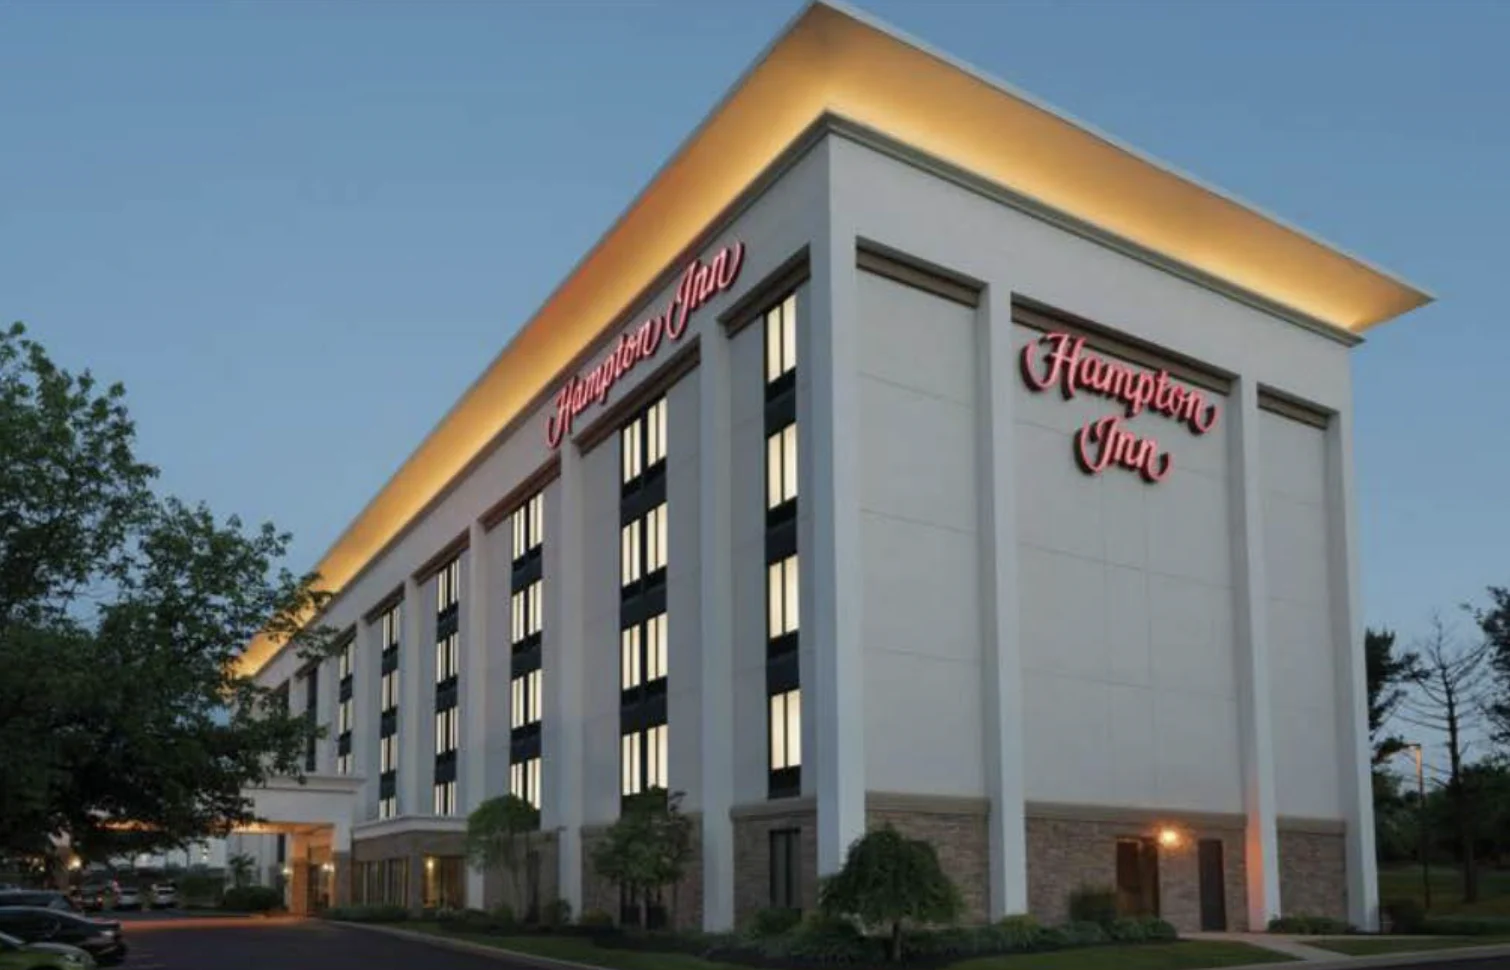
142-room Inn – Reading
Hotel
Multi-Tenant Industrial Property
Industrial
O’Connor-Masse Family Trust
Refinance
RJED Akron CRE Deal Case Study | AVANA CUSO
Acquisition
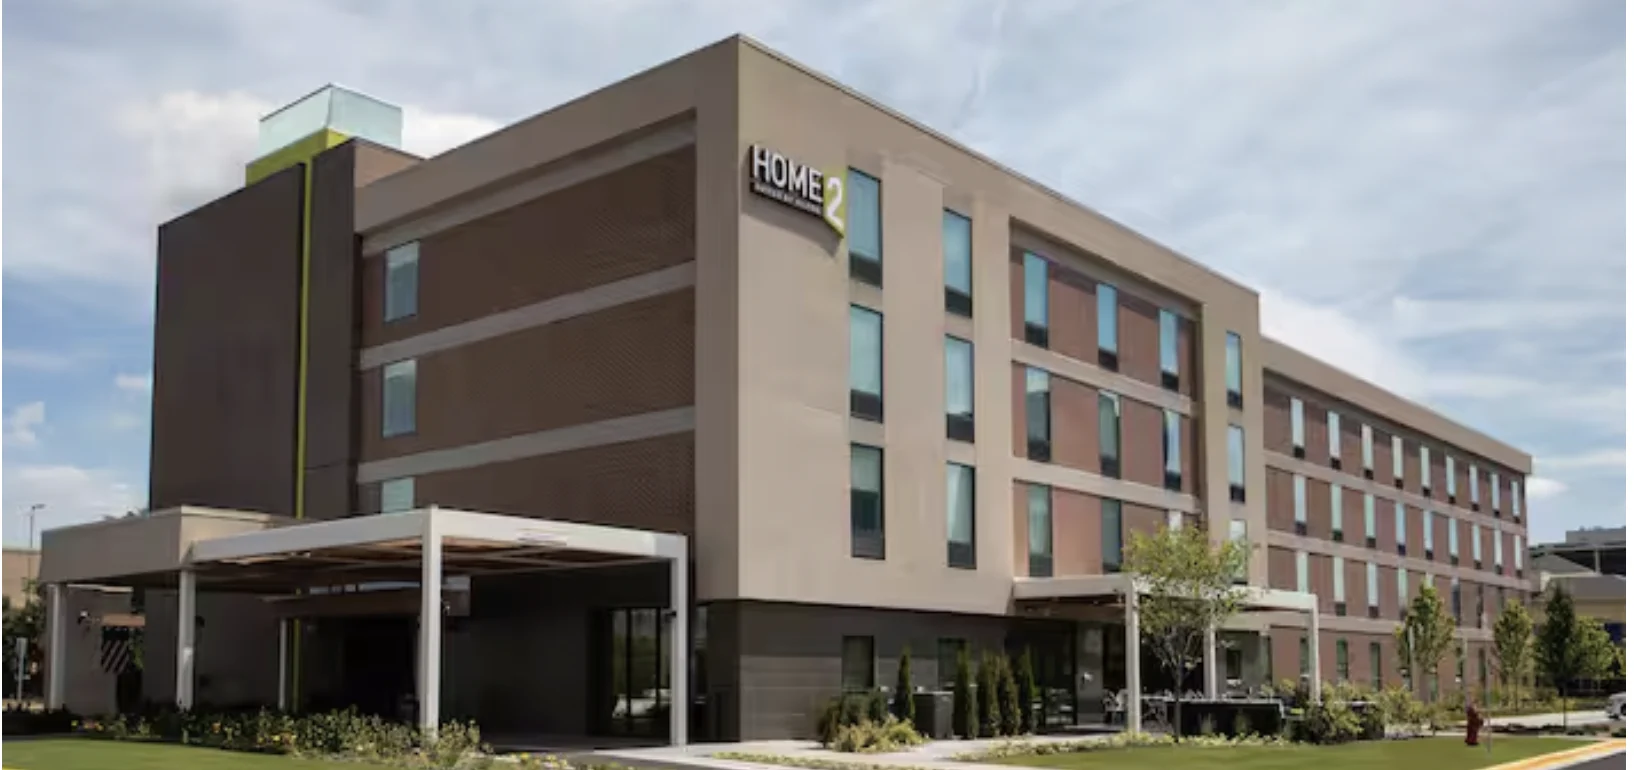
107-room Home2 Suites Deal
AcquisitionGrow Your CRE Program With a Partner Built for Credit Unions
Client Testimonials

Aaron Klein
Commercial Mortgage Capital, Inc.AVANA CUSO’s strength is in understanding the unique character of every transaction and borrower, and reacting in real-time to solve problems to get deals closed.
Paula Lehn
Chief Executive Officer, FAST Federal Credit UnionAVANA CUSO has provided FAST CU with great LP opportunities which in turn allows us to strategize our balance sheet to best serve our members.
Our Team
Sundip Patel
Co-Founder & Chief Executive Officer
Sanat Patel
Chief Lending Officer
Mae Julian
Global Controller
Brianna Vaughan
EVP, Credit Union Success
Joy Hekking
VP, Servicing
Candace Sheets
EVP, Head of Credit
Josephine Aquino
Customer Success Manager
Frequently Asked Questions
What property types and loan sizes do you lend on?
We lend on owner-occupied and investor-owned commercial real estate through four programs: SBA 504, conventional, bridge and construction, with loans from $1MM to $30MM. Property types include hospitality, industrial, manufacturing, medical office, mixed-use, multi-family, restaurant, retail, self-storage and warehouse. See our loan programs for terms.
What is a CUSO?
A credit union service organization (CUSO) is a company that provides specialized services to credit unions. AVANA CUSO focuses on commercial real estate: we originate, underwrite and service CRE loans, offer them to credit unions as participations, and provide à la carte lending services.
What information is needed to evaluate a participation opportunity?
Common review materials may include collateral and property details, borrower/sponsor background, requested structure, and supporting financial documentation. Third-party reports and additional items may be required depending on the loan and underwriting. Reviewing a submission does not imply approval.
Do you provide loan servicing after closing?
Yes—servicing support may include post-close administration, routine loan servicing activities, and reporting access based on the agreed scope. This is designed to help credit unions maintain ongoing visibility and operational consistency. Servicing and reporting support vary by engagement and loan type.
How do you approach underwriting and due diligence?
We use a structured review process designed to support consistent evaluation and decision-making, with documentation requirements aligned to the transaction and the participating credit union’s policies. Due diligence commonly includes review of the borrower/sponsor, collateral and property details, and supporting third-party items as applicable.
Recent Blog Posts
Get in Touch With Us
Participation, Origination and Servicing in One Platform
A Credit Union-First Approach
SBA 504, Conventional, Bridge and Construction Loans, $1MM–$30MM
Have any questions?
