
Purchase Financing for Owner-Occupied and Investment Property
Buying a building for your business or adding an investment property? The right loan to buy commercial property depends on how you’ll use it and how soon you need to close. Apply once, and AVANA matches your purchase to SBA 504, Conventional or Bridge financing.
SBA 504 requires your business to occupy at least 51% of the building. Down payment is 15% for startups or special-purpose property, and 20% if both apply.
Which Acquisition Loan Fits Your Purchase?
SBA 504 finances projects up to $20MM total, conventional loans run from $1MM to $15MM, and bridge loans run from $10MM to $30MM.
Your Business Will Occupy the Building
If your business will use at least 51% of the space, an SBA 504 loan can finance up to 90% of the project. Your payment stays long-term and predictable.
You're Buying a Stabilized Investment Property
The building is leased and earning. A conventional term loan fixes your rate for five years, with no owner-occupancy requirement and no prepayment penalty.
The Property Needs Work or the Closing Can't Wait
A bridge loan funds the purchase now, interest-only, while you lease up or reposition. You refinance once the property stabilizes.
Who Qualifies
- Guarantors have a FICO score of 680 or higher
- Experience: 3+ years of operating history for Conventional; 5+ years in commercial real estate for Bridge
- SBA 504 borrowers are for-profit U.S. businesses within SBA size standards
- The property produces income or will house your operating business
- Principals provide a full-recourse guaranty on Conventional and Bridge loans
You don’t have to pick a program before you apply. One application covers SBA 504, Conventional, Bridge and Construction, and AVANA points your purchase to the one that fits.
What Acquisition Loans Don't Fund
Ground-up construction, working capital, inventory and first-time sponsors on bridge loans. SBA 504 doesn’t fund pure investment or rental property. For a ground-up hotel, see hotel construction loans.
Loan Programs to Buy Commercial Property
For a building your business will occupy (51%+). Up to 90% of project cost on projects up to $20MM total, with as little as 10% down.
$1MM–$15MM for a stabilized, income-producing property, up to 75% of value (65% for franchised hotels and restaurants). Fixed for five years at the 5-Year CMT + 2.00%–3.00%.
$10MM–$30MM for a property in transition or a fast closing. Interest-only at 1-Month Term SOFR + 4.50%–7.00% for up to 3 years, with annual extension options.
How Long an Acquisition Loan Takes to Close
Conventional
About 30–45 days from a signed Letter of Intent.
Bridge
About 45 days from LOI acceptance.
SBA 504
Most SBA 504 loans close in about 45 to 75 days.
Soft quote. Your soft quote comes within 1–2 business days of your pre-qualification materials. For Conventional and Bridge deals that fit, a Letter of Intent typically follows within 3–5 business days.
What can slow your closing:
- The appraisal: usually the main pacing item, and often 3–4 weeks on SBA 504 deals
- Third-party reports: environmental, property condition, and title and survey
- Incomplete financials: missing T-12s, rent rolls or guarantor statements
Why Borrowers Work with AVANA
What You'll Need
At Application
Last year’s tax return or financial statement, plus a trailing 12-month P&L and balance sheet.
During Prescreen
An executive summary or offering memorandum, and an organizational chart, which is required before a Letter of Intent.
Financials
3 years of tax returns or historical financial statements, a T-12 dated within 90 days, a debt schedule and the current rent roll for leased assets.
Hotels
STR reports, plus an STR Trend Report covering as many years as you have for a brand conversion.
Each Guarantor
A personal financial statement with a schedule of real estate, a personal debt schedule, a resume and 3 years of personal tax returns.
Improvements
The scope of work and a budget.
Commercial Property Purchases We've Helped Finance
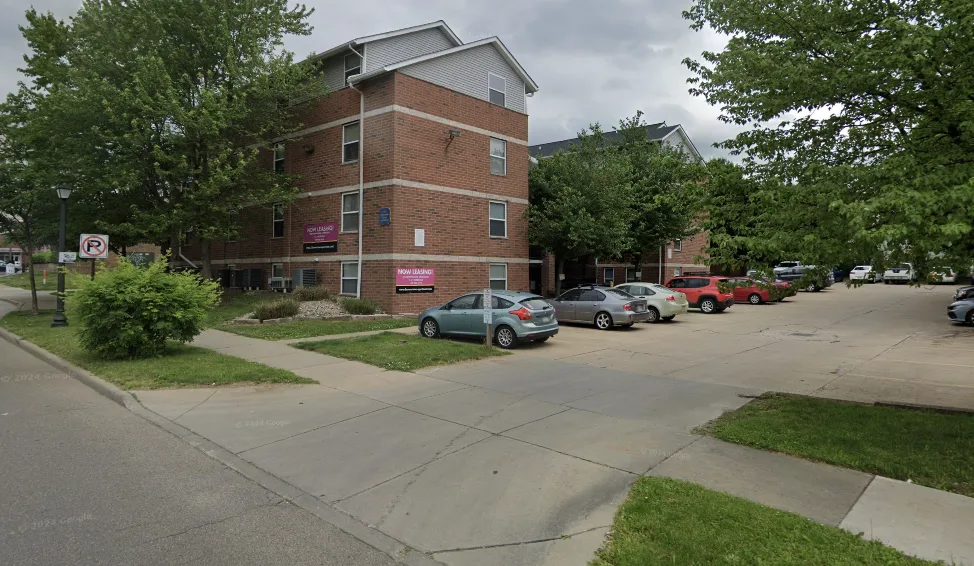
RJED Akron CRE Deal Case Study | AVANA CUSO
Acquisition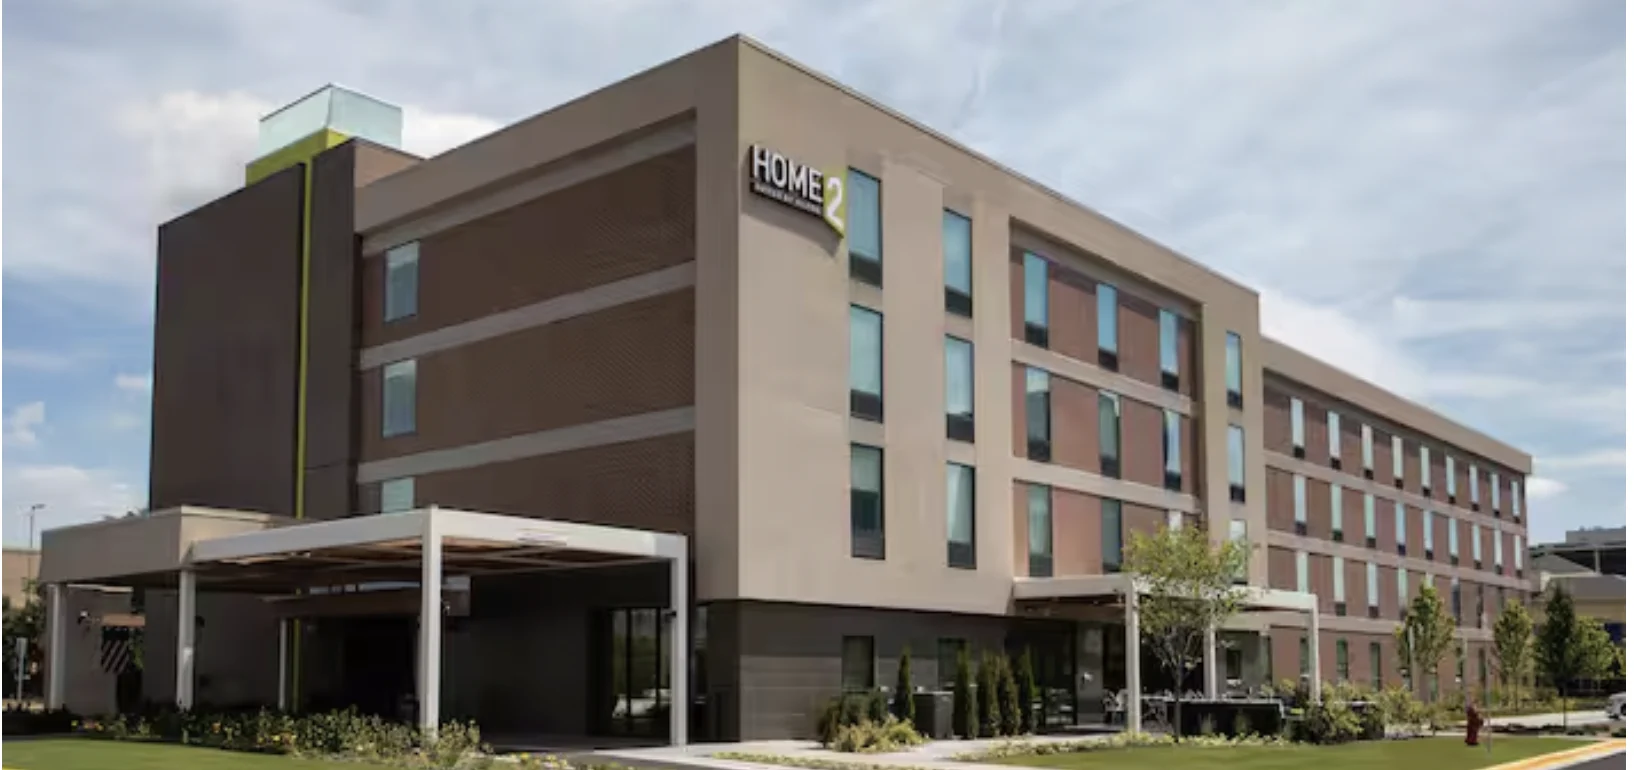
107-room Home2 Suites Deal
Acquisition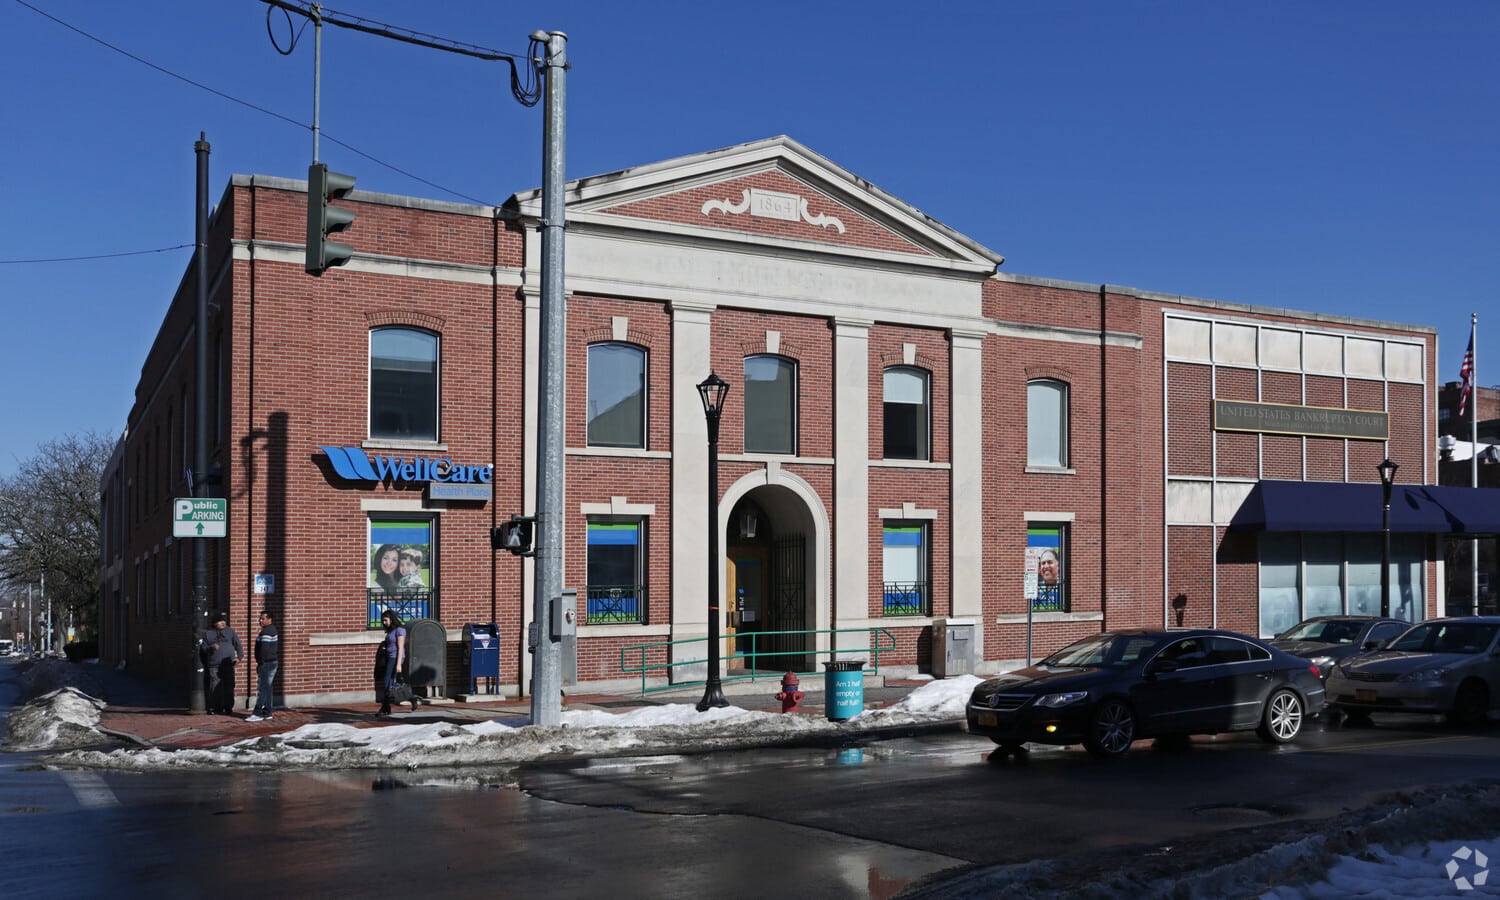
Office Building Acquisition Deal
Acquisition
Plaza Acquisition Deal
Acquisition
6-unit multi-family property
Acquisition
Industrial Building Acquisition
AcquisitionCommercial Property Purchase Loan FAQs
How much do I need to put down on a commercial property?
As little as 10% with SBA 504, or at least 25% with a conventional loan. SBA 504 rises to 15% for startups or special-purpose property, and to 20% if both apply.
Conventional loans finance up to 75% of value, or 65% for franchised hotels and restaurants, so plan on 35% there. Bridge loans cap at the lesser of 75% as-is or 70% as-stabilized value.
Can I get a fixed rate on a purchase loan?
Yes. A conventional term loan is fixed for five years at the 5-Year CMT plus 2.00%–3.00%, with no prepayment penalty. On an SBA 504 loan, the SBA debenture is usually fixed for up to 25 years.
Bridge loans float over the 1-Month Term SOFR, since they're built for short holds of up to 3 years.
Can I buy a property and renovate it with the same loan?
Yes, as long as the work isn't ground-up construction. Property improvements are an eligible use under SBA 504 and conventional term loans.
Bridge loans can fund renovations before you refinance into SBA 504 or a term loan. Send the scope of work and a budget with your application.
Can I buy a hotel with an acquisition loan?
Yes. Franchised hotels are eligible under all three programs. Conventional loans go up to 65% of value on franchised hotels, with net operating income of at least 1.35x debt service.
Eligible brands include Marriott, Hilton, IHG and Hyatt. Send STR reports with your application. If you'll operate the hotel, compare SBA 504.
What if the building I'm buying isn't fully leased yet?
Then a conventional loan isn't the right fit yet, because it's built for stabilized, income-producing property. A bridge loan can fund the purchase while you lease up.
Once occupancy and income are where a permanent lender needs them, you refinance into a conventional term loan. Plan that exit before you apply, because underwriting tests it.
Do I need to know which program I want before I apply?
No. You apply once with AVANA, and the team reviews your purchase and points it to the program that fits. The same application covers SBA 504, Conventional, Bridge and Construction.
You'll get a soft quote within 1–2 business days of sending your pre-qualification materials. Compare programs side by side in our loan programs comparison.
Get a Soft Quote on Your Commercial Property Purchase
Tell us about the property, the price and how you’ll use it. We’ll come back with a soft quote within 1–2 business days.
Our Team
Chief Lending Officer