
Apartment Building Loans to Hold, Reposition or Refinance
Holding a stabilized apartment building, or buying one to renovate and lease up? AVANA’s apartment building loans run from $1MM to $30MM through two programs, up to 75% LTV. Apply once, and we match your property to the one that fits.
Soft quote in 1–2 business days. One application covers every AVANA program.
Which Multifamily Loan Fits Your Business Plan?
Conventional loans run from $1MM to $15MM, and bridge loans run from $10MM to $30MM.
Your Building Is Stabilized
A conventional term loan buys, refinances or recapitalizes a stabilized apartment building. It amortizes over 30 years, with no prepayment penalty.
You're Renovating or Repositioning
A bridge loan funds acquisitions, heavy renovations and repositionings ahead of agency or long-term take-out. It’s interest-only for up to 3 years.
Your Bridge Loan Is Coming Due
Once the building stabilizes, a conventional term loan moves it out of short-term debt into permanent financing.
The Building Has Ground-Floor Retail
Apartments over shops are financed as mixed-use property, through a conventional term loan.
Multifamily Loan Eligibility
- The property is garden-style, mid-rise, workforce or student housing
- It’s market-rate, mixed-income or LIHTC-supported, subject to location and performance
- You have a clear business plan for the building
- You have 3+ years of operating history for Conventional, or 5+ years of experience for Bridge
- Guarantors have a FICO score of 680 or higher, and principals can provide a full-recourse guaranty
What We Don't Finance for Multifamily
Ground-up construction of apartment buildings. SBA 504 doesn’t fund rental property, so it isn’t offered for multifamily. Bridge doesn’t fund first-time sponsors or projects without a credible exit plan.
What You Can Finance
- Stabilized or value-add acquisitions
- Refinancing, including cash-out for approved business purposes
- Interior and exterior renovations
- Amenity upgrades and unit repositionings
- Partner buyouts
- Bridging to agency take-out
Apartment Building Loan Programs
$1MM–$15MM, up to 75% of value at 1.25x DSCR, with 30-year amortization. Fixed for five years at the 5-Year CMT + 2.00%–3.00%, with no prepayment penalty.
$10MM–$30MM at 1-Month Term SOFR + 4.50%–7.00%, up to 75% of as-is or 70% of as-stabilized value. Interest-only for up to 3 years, with annual extension options.
What Lenders Look at on a Multifamily Loan
Apartment loans are underwritten on how the building performs today and where your plan takes it. Expect questions on these five points.
Occupancy and Rent Roll
Send the current rent roll and a T-12 dated within 90 days. Conventional loans are for stabilized buildings, so lease-up deals go to Bridge.
Debt Service Coverage
Conventional multifamily loans need net operating income of at least 1.25x debt service. The 30-year amortization keeps monthly debt service lower.
Exit Plan
Bridge loans need a documented exit: a refinance, a sale or lease-up to stabilization. Agency or long-term take-out is a common path.
Renovation Scope
For renovations, amenity upgrades or unit repositionings, send the scope of work and a budget with your application.
Sponsor Experience
Bridge needs 5+ years of relevant experience. Conventional asks for 3+ years of operating history.
How Multifamily Financing Works
Soft Quote
Send your application. You get a soft quote within 1–2 business days.
Letter of Intent
For deals that fit, a Letter of Intent typically follows.
Underwriting
Third-party reports and final credit approval. The appraisal, environmental report and property condition report drive most of the timeline.
Closing
About 30–45 days from a signed LOI for Conventional, and about 45 days from LOI acceptance for Bridge.
Why Borrowers Work with AVANA
What You'll Need
At Application
Last year’s tax return or financial statement, plus a trailing 12-month P&L and balance sheet.
During Prescreen
An executive summary or offering memorandum, and an organizational chart, which is required before a Letter of Intent.
Financials
3 years of tax returns or historical financial statements, a T-12 dated within 90 days, a debt schedule and the current rent roll for leased assets.
Each Guarantor
A personal financial statement with a schedule of real estate, a personal debt schedule, a resume and 3 years of personal tax returns.
Improvements and Refinances
Improvements: the scope of work and a budget.
Refinances: the current loan balance and status, prepayment penalty details and your cost basis.
Multifamily Loans We've Helped Close

38-Unit Multifamily in Newark, NJ
Multifamily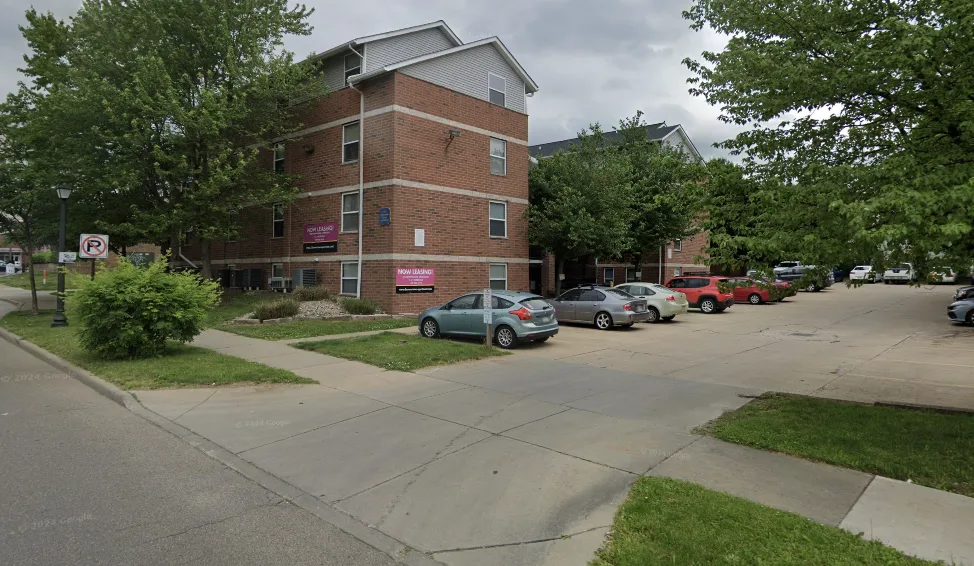
RJED Akron CRE Deal Case Study | AVANA CUSO
Acquisition
6-unit multi-family property
Acquisition
Multifamily 12-Unit Apartment Complex
Multifamily
Terravita Apartments Project
Multifamily
41-unit Inn & Suites
MultifamilyMultifamily Loan FAQs
How much do I need to put down on an apartment building?
At least 25%, since both programs lend up to 75%. Conventional loans go up to 75% of appraised value. Bridge loans go up to 75% of as-is or 70% of as-stabilized value, whichever is less.
SBA 504's lower down payment isn't available here, because SBA 504 doesn't fund rental property. See how SBA 504, Conventional and Bridge compare on our loan to buy commercial property page.
Can I get a 30-year loan on an apartment building?
Yes, for the amortization. Conventional multifamily loans amortize over up to 30 years, compared with 25 for other property types. The loan term itself is 5–10 years.
The rate is fixed for the first five years at the 5-Year CMT + 2.00%–3.00%, and resets after year 5 on 10-year loans. There's no prepayment penalty.
Can I refinance an apartment building and take cash out?
Yes, for approved business purposes. A conventional loan refinances a stabilized building up to 75% of value, with 1.25x debt service coverage.
If the building is mid-renovation or still leasing up, a bridge loan can pay off maturing debt ahead of stabilization. Once it stabilizes, you can refinance into a conventional term loan. See every option on our commercial mortgage refinancing page.
Can I buy out my partner in an apartment building?
Yes. Partner buyouts are an eligible use of a conventional term loan. You use the building's existing equity to acquire your co-owner's interest, within the 75% limit.
List everyone with 20% or more ownership, plus the proposed guarantors, in your application. Guarantors need a 680+ FICO score and give a full-recourse guaranty.
Is there a minimum loan size for a multifamily bridge loan?
Yes, bridge loans start at $10MM and run up to $30MM. Conventional term loans cover $1MM–$15MM for stabilized buildings.
Bridge pricing is 1-Month Term SOFR + 4.50%–7.00%, depending on asset class, risk and sponsor strength. Extension fees typically run 0.25%–0.50%.
Can I use a bridge loan until I get agency financing?
Yes. A bridge loan can carry the building through lease-up or stabilization, then you refinance into agency or other long-term debt. It's interest-only for up to 3 years, with annual extension options.
You'll need a documented exit plan, 5+ years of relevant experience and guarantors with a 680+ FICO score.
Get a Soft Quote on Your Multifamily Loan
Tell us about the building, its occupancy, the amount you need and your business plan. We’ll come back with a soft quote within 1–2 business days.
Our Team
Chief Lending Officer