CRE Loan Origination Support for Credit Unions

AVANA CUSO provides tech-enabled deal sourcing and intake support, designed to fit your credit union’s strategy, controls, and decision process

Two people collaborating at a wooden table, using laptops and taking notes with coffee in a cozy environment.
trusted partnerships

Strategic CRE Origination – Built for the CU Model

AVANA CUSO supports both Credit Union-sourced and AVANA-sourced commercial real estate loans

Through the Credit Union Portal and coordinated pipeline tracking, we help credit unions expand access to quality CRE opportunities while maintaining visibility and control.

What We Provide

For credit union-sourced loans, we collaborate on origination strategy and fee sharing. For AVANA-sourced opportunities, we manage coordination and placement through our participation network.

The result: expanded opportunity without expanding operational burden.

  • Loan Sourcing and Pipeline Management

    We source CRE borrowers and manage the pipeline, so qualified deals keep coming.

  • Borrower Pre-Screening and Initial Qualification

    Borrowers are screened before a deal reaches your credit team.

  • Coordinated Origination Support

    We coordinate each origination step with your team, from intake to credit review.

  • Screened Deals in the Credit Union Portal

    Review screened opportunities, documents and status in one portal.

  • Co-Branded Marketing Programs to Generate Member CRE Demand

    Joint campaigns that build CRE demand among your own members.

Loan Programs We Originate

AVANA originates all four programs. SBA 504 and Conventional Term loans can be funded by credit unions through AVANA CUSO, while Bridge and Construction loans are funded by other lenders.

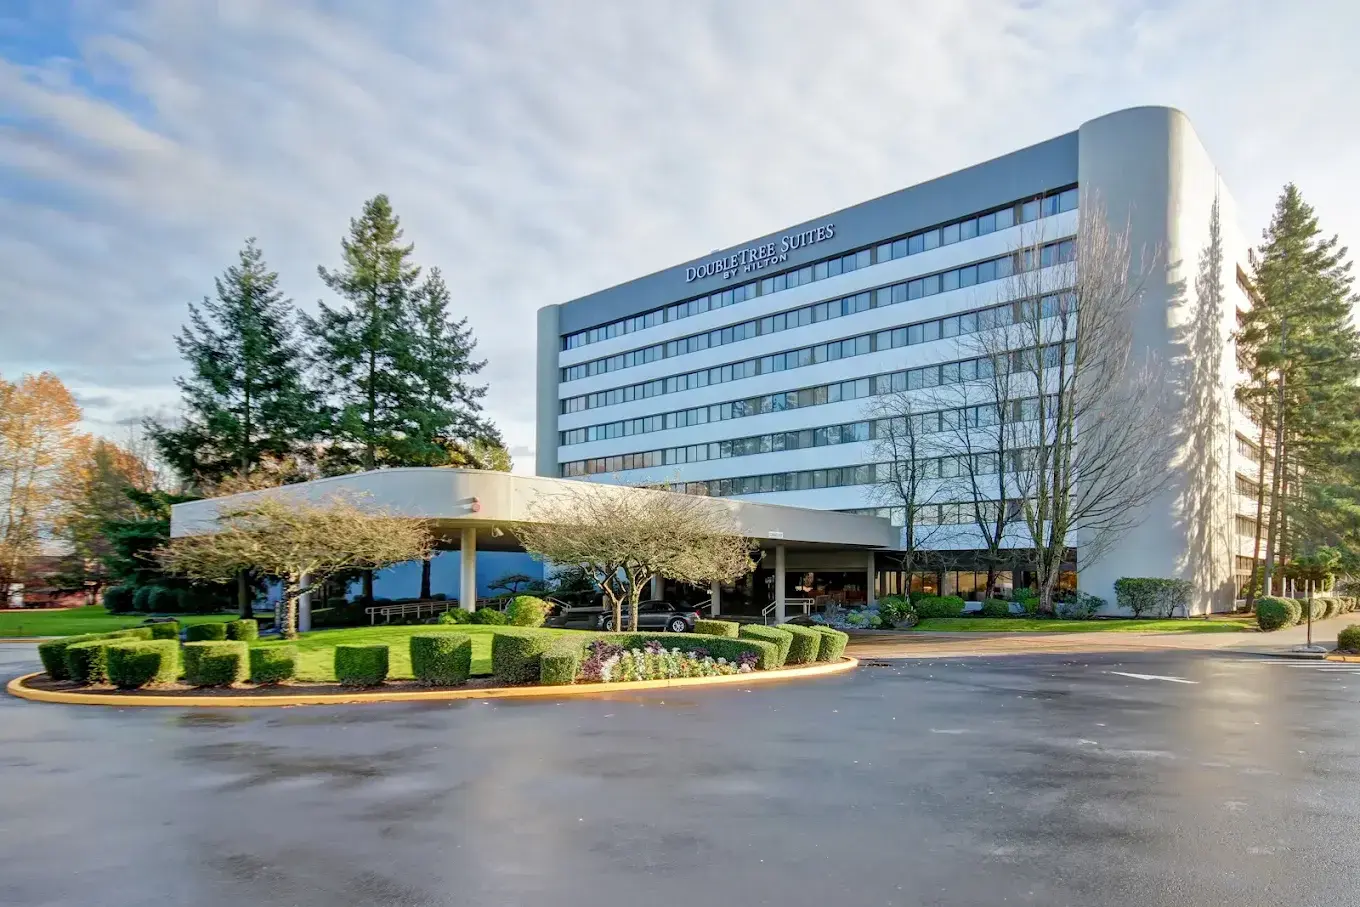
Modern office buildings with large glass windows and unique architectural design under a cloudy sky.

For a building your business occupies (51% or more). Up to 90% of project cost (85% special-use) and up to $20MM total, with the SBA debenture fixed for up to 25 years.

Explore SBA 504 Program →

Group discussion in a cozy living room, featuring individuals engaged in conversation and using laptops.

For a stabilized, income-producing property. $1MM–$15MM, fixed for five years at the 5-Year CMT + 2.00%–3.00%, up to 75% of value, with no prepayment penalty.

Explore Conventional Program →

Modern glass skyscraper rising above textured concrete buildings against a soft blue sky, showcasing urban architecture.

For a property in transition or a deal that needs to close fast. $10MM–$30MM, interest-only for up to 3 years at 1-Month Term SOFR + 4.50%–7.00%.

Explore Bridge Program →

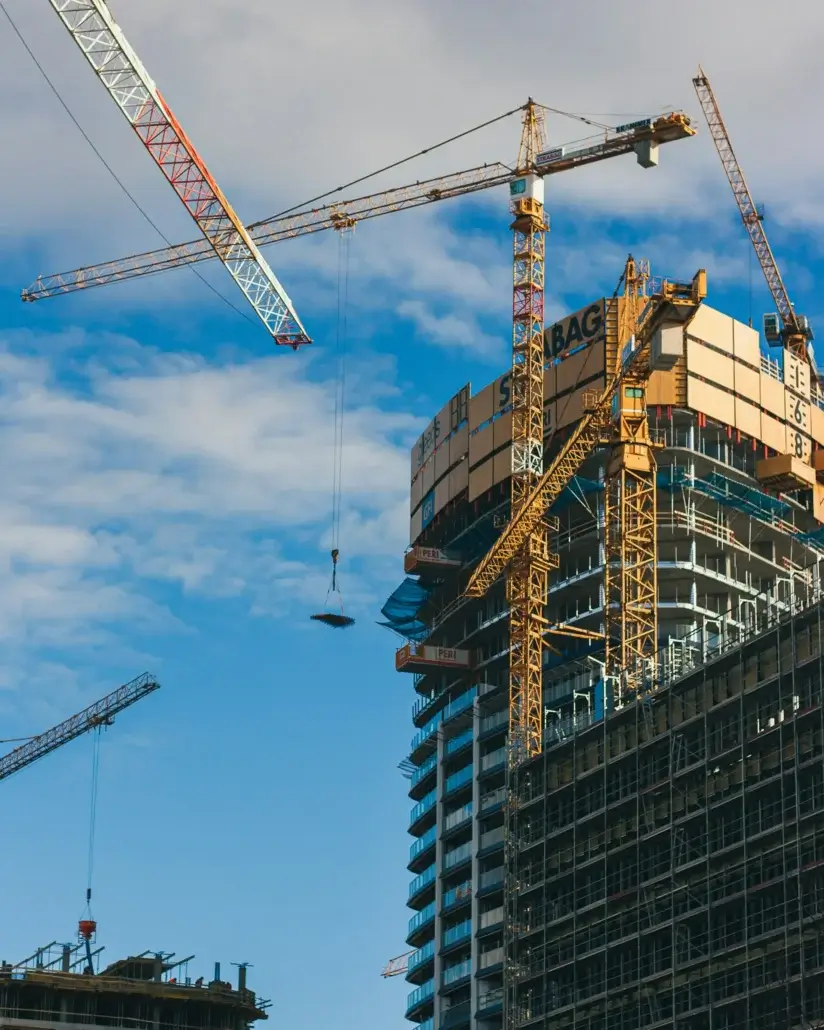
Construction site with cranes and a building under development against a blue sky, showcasing urban architecture and progress.

For franchised hotels: ground-up builds, expansions, brand conversions and major renovations or PIPs. $5MM–$30MM, with interest only on drawn funds.

Explore Construction Program →

Our working process with Credit unions

How It Works

01

Align on Strategy and Scope

We agree on your CRE lending goals, target property types and the origination services you need.

02

Source, Screen and Underwrite

Deals sourced by your credit union or by AVANA are screened, underwritten and checked before they reach your team.

03

Review in the Credit
Union Portal

Approved deals are published in the Credit Union Portal with their details and documents, ready for your team to review.

04

Your Team Decides

Your credit union reviews each deal against its own standards and keeps final approval.

Client Testimonials

David Stepanchak, SVP

George Smith Partners, Inc.

AVANA CUSO continues to provide a much needed product supported by their ability to underwrite using common sense metrics. Their step-down prepayment structure and capacity to lend in most markets adds a flexibility most portfolio lenders will not offer

Screened Deals, One Portal and Co-Branded Marketing

Bring More Qualified CRE Deals to Your Credit Union

Why AVANA CUSO

Built Around Credit Union Governance

Scope, reporting and documentation are aligned to your policies and to how your board and committees review risk.

Two Ways to Grow Your Pipeline

Work deals your credit union sources, or access opportunities AVANA sources and places through its participation network.

Technology-Enabled Reporting and Workflow Discipline

Structured processes and reporting tools can help teams stay organized, informed, and audit-ready.

1998
Founded
28
Years of CRE lending
$6.5Bn
Total originations
$0.8Bn
Assets under management

Frequently Asked Questions

Loan Originations is designed to support the front end of the commercial lending lifecycle. Depending on your needs, scope may include deal sourcing, screened deals delivered in the Credit Union Portal, and co-branded marketing support to help present the program consistently. Many credit unions use origination support to improve intake quality and workflow consistency by capturing key information early, organizing documentation, and creating clearer handoffs into underwriting or credit administration. Engagements can be structured to complement your existing team and processes rather than replace them.

No. AVANA CUSO can support sourcing, intake, organization, and file readiness, but your credit union retains credit authority and final approval. Credit decisions remain subject to your underwriting standards, internal policies, and required committee or board processes. This structure is intentional because it supports clear governance while adding capacity and process support. If your team needs additional help beyond origination, such as credit analysis, spreading, or documentation and closing support, that work can be scoped separately under Lending and Credit Administration.

Borrowers apply through AVANA’s loan application. AVANA screens, underwrites and checks each deal, and deals suited to credit union financing are published in the Credit Union Portal. Your team reviews the opportunity details and documents there, and your credit union keeps final approval.

AVANA originates SBA 504, Conventional Term, Bridge and Construction loans across common commercial real estate property types. SBA 504 and Conventional Term loans can be funded by credit unions through AVANA CUSO, while Bridge and Construction loans are funded by other lenders. Program availability and eligibility depend on borrower profile, collateral, documentation, and your credit union’s underwriting and approval requirements. If your team has a defined credit box, or wants help tightening one, sourcing and intake criteria can be aligned to those requirements so opportunities are introduced and packaged in a way that supports your review process.

We differentiate by where the service sits in the lifecycle. Loan Originations focuses on deal sourcing, screening, underwriting and delivering deals through the Credit Union Portal, and packaging for initial review. Lending and Credit Administration focuses on underwriting workflow support, including credit analysis, financial spreading, document processing, and closing readiness. Loan Servicing focuses on post-close operations, ongoing administration, and servicing-related visibility. Keeping these stages distinct helps your team select the right support at the right time.

Ready to Strengthen Your Origination Workflow?

Pre-Screened, Ready-To-Review Deals

SBA 504 and Conventional Programs

Ready-To-Review Deals in One Portal

Our Team

Sundip Patel

Co-Founder & Chief Executive Officer
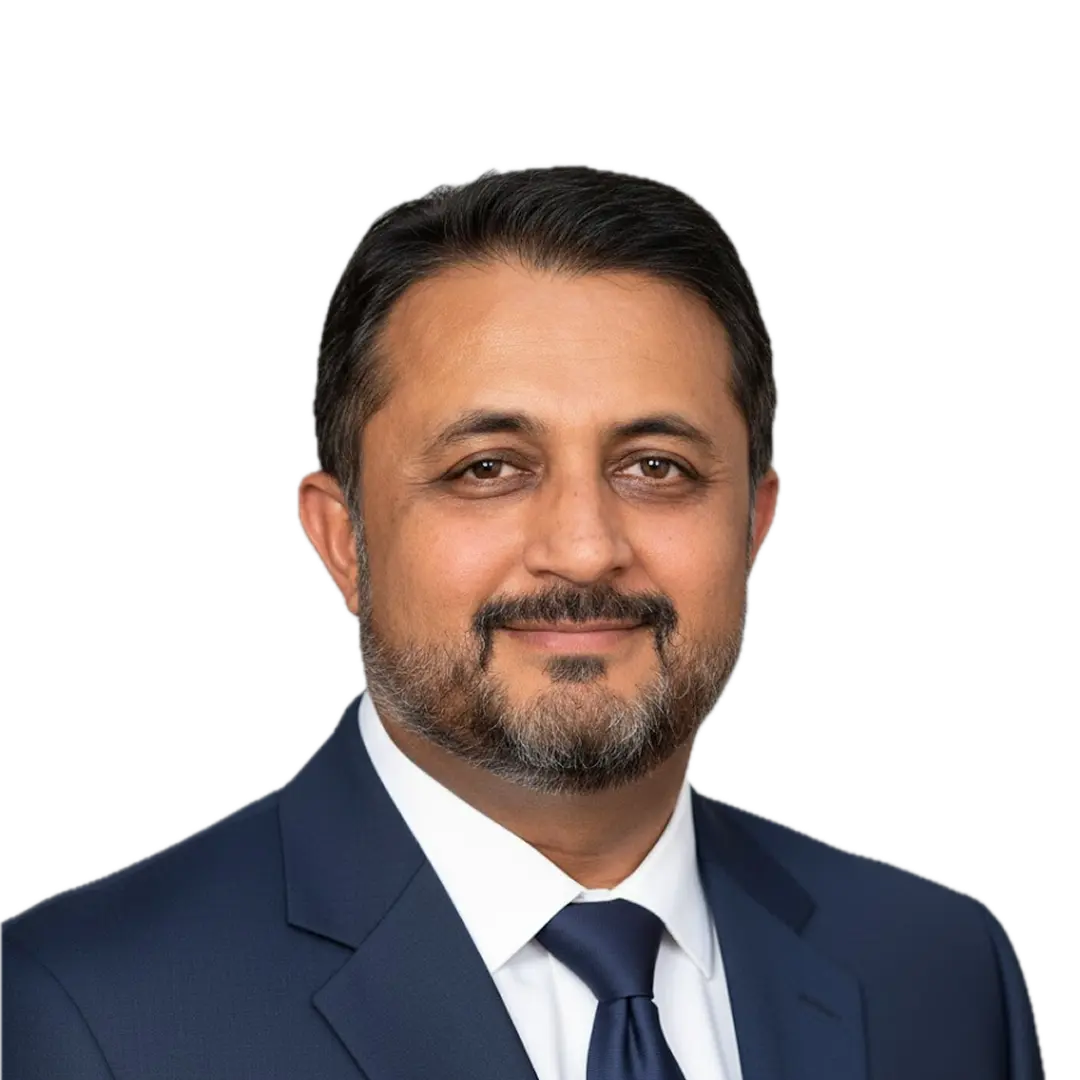
Sanat Patel

Chief Lending Officer
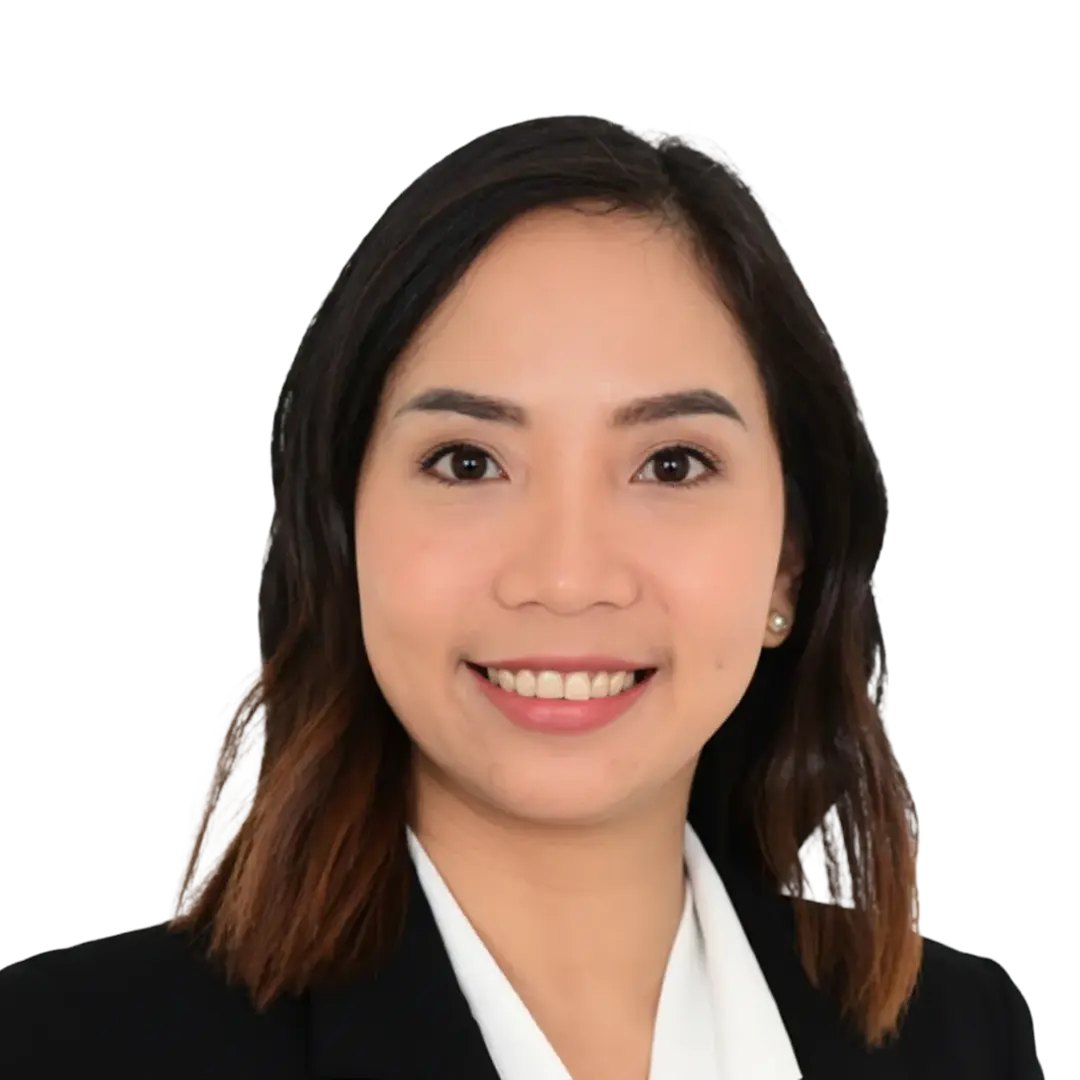
Mae Julian

Global Controller
Brianna Vaughan

EVP, Credit Union Success
Joy Hekking

VP, Servicing
Candace Sheets

EVP, Head of Credit
Josephine Aquino

Customer Success Manager